Super Micro Computer (SMCI) Stock Forecast 2026–2030
Super Micro Computer (SMCI) stock forecast for 2026 to 2030. See Wall Street price targets, revenue growth trends, and bull, base, and bear valuation models.
On this page
- What Super Micro Computer does and how it makes money
- Where the business stands: sales growth and profit trends
- SMCI stock forecast for the next 12 months: what analysts expect
- What is the SMCI stock forecast for 2030? Three scenarios
- The bear case
- The base case
- The bull case
- Risks to weigh
- What to watch next
- FAQ
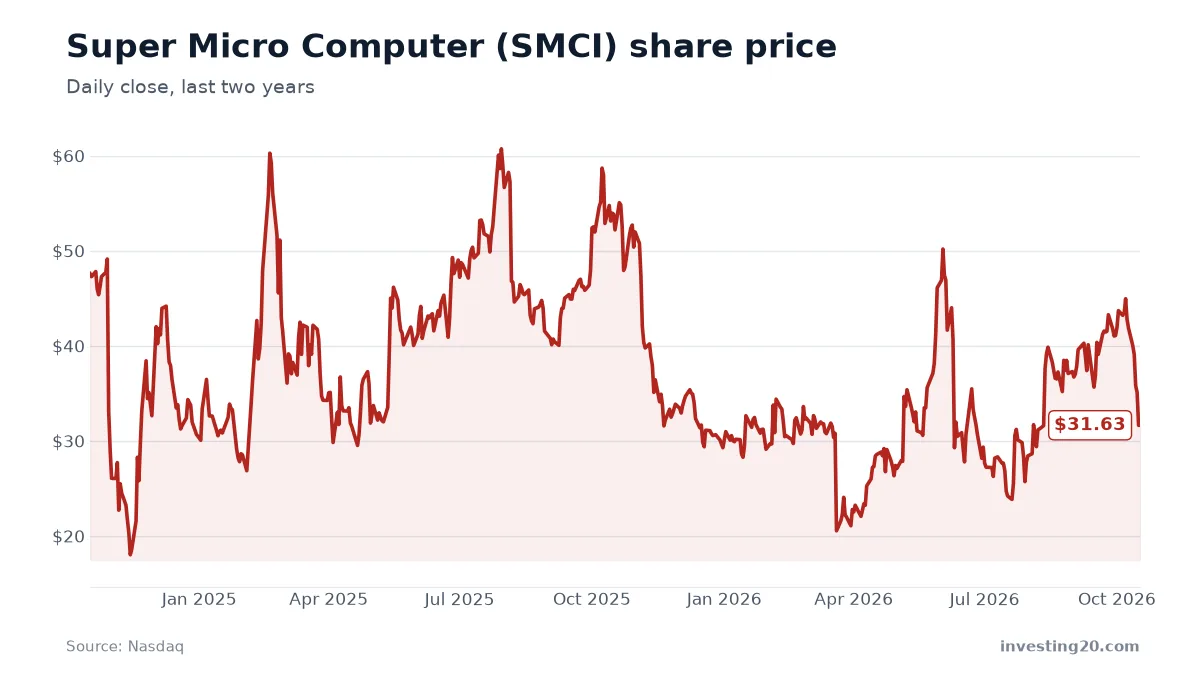
Super Micro Computer trades around $31.63 after a turbulent couple of years that took the shares from a peak of $60.71 in July 2025 down toward their 52-week lows. If you follow enterprise hardware and artificial intelligence infrastructure, this SMCI stock forecast breaks down where the business stands today and what realistic financial outcomes could look like through 2030.
Long-range stock forecasts are not guarantees or certain predictions. Instead, think of them as structured scenarios: they help you understand what revenue growth rates, profit margins, and valuation multiples the market is already pricing in, and what needs to go right for the stock to deliver solid returns.
| Share price | $31.63 (Oct 15, 2026) |
| Market value | about $20.8 billion |
| 52-week range | $19.48 – $56.60 |
| Revenue, last 12 months | about $39.1 billion |
| Revenue growth, last fiscal year | 78% |
| Net income, last 12 months | about $2.2 billion |
| Price-to-sales | about 0.5× |
| Price-to-earnings | about 9× |
| Analyst 12-month target | average $39.67 (range $15 – $51); 2 buy, 9 hold, 3 sell |
Market data from Nasdaq as of October 17, 2026. Check current figures before making any decision.
The table above summarizes where Super Micro Computer stands as of October 2026. The shares trade at roughly 9.3 times net income and just 0.5 times sales, reflecting a market that is deeply skeptical of whether the company’s rapid expansion can last.
What Super Micro Computer does and how it makes money
Super Micro Computer operates out of San Jose, California, providing what it calls Application-Optimized Total IT Solutions. In plain English, the company designs and builds high-performance server, storage, and networking systems. Its product catalog spans AI-optimized servers, modular motherboard systems, power supplies, chassis, switches, software, and complete rack-level integration.
The business earns money primarily by selling these enterprise hardware systems to cloud service providers, large corporations, AI developers, and telecommunications operators. Rather than relying entirely on third-party contract manufacturers, Super Micro designs and builds products in-house across facilities in the United States, Taiwan, and the Netherlands.
This in-house manufacturing footprint lets the company configure custom server architectures quickly when chipmakers release new processors. Management markets this modular setup as “Green Computing,” designed to lower power consumption, improve total cost of ownership, and reduce cooling needs for power-hungry data centers.
Where the business stands: sales growth and profit trends
Financially, Super Micro’s top-line numbers have expanded at a breathtaking clip over the past three fiscal years. For the fiscal year ending June 30, 2024, the company generated $15.0 billion in revenue. That figure climbed to $22.0 billion in fiscal 2025 and reached $39.1 billion in the fiscal year ending June 30, 2026. That represents a 77.8% jump in annual sales in the most recent fiscal year alone.
Profitability has followed a similar path. Net income doubled from $1.0 billion in fiscal 2025 to $2.2 billion in fiscal 2026. Quarterly performance across the last fiscal year showed accelerating top-line momentum, climbing from $5.02 billion in the quarter ending September 2025 to $12.68 billion in December 2025, before settling at $10.24 billion in March 2026 and $11.12 billion in June 2026.
Super Micro has also repeatedly outperformed quarterly expectations. For the quarter ending June 2026, the company reported diluted earnings per share of $1.62 against a consensus analyst estimate of $0.56, an earnings surprise of 189.29%. The prior three quarters saw earnings beats of 23.64%, 36.59%, and 36.84%. Yet despite this streak of outperformance, the stock trades at $31.63, down 33.5% from $47.59 on October 17, 2024.
Assessing volatile growth stories that swing between extreme hype and deep discounts is a common challenge across modern tech; you can see similar valuation debates in our Tesla (TSLA) stock forecast and our look at Robinhood Markets (HOOD) stock.
SMCI stock forecast for the next 12 months: what analysts expect
Looking ahead over the coming year, the consensus SMCI price target from Wall Street analysts tracked by Nasdaq stands at $39.67. If the stock meets that average target, investors would see a return of about 25.4% from the current price of $31.63.
The range of targets shows just how divided market watchers are on the company’s near-term trajectory:
- High target: $51.00 (a potential upside of roughly 61%)
- Average target: $39.67 (an upside of about 25.4%)
- Low target: $15.00 (a potential downside of over 52%)
Analyst ratings lean toward caution. Of the 14 analysts covering the stock, 9 rate it a hold, 2 rate it a buy, and 3 rate it a sell. Consensus forecasts call for earnings per share to hit $3.94 for the fiscal year ending June 2027 (based on 7 analysts) and $4.90 for the fiscal year ending June 2028 (based on 5 analysts).
For the stock to push toward the higher end of the 12-month range, Super Micro will need to prove that gross margins can hold up as server competition intensifies, and that customer demand remains steady rather than cyclical. If margins compress or server orders slow, the stock risks testing the lower end of that forecast spread.
What is the SMCI stock forecast for 2030? Three scenarios
To model where SMCI shares could trade by 2030, we look at long-term revenue growth, the price-to-sales multiple the market assigns to that revenue, and potential share dilution. Fast-growing hardware companies rarely maintain high growth rates forever; revenue expansion naturally tapers as total dollar volume increases.
Today, Super Micro trades at a low price-to-sales multiple of roughly 0.5. At that multiple and factoring in mild dilution, the business needs about $46.1 billion of revenue in 2030 for the shares to be worth today’s $31.63. Since trailing 12-month sales already sit at $39.1 billion, today’s stock price assumes very little growth over the rest of the decade.
Here is how three distinct financial outcomes could look by 2030:
| Scenario | Revenue growth per year | 2030 revenue | Price-to-sales | Shares | Implied share price |
|---|---|---|---|---|---|
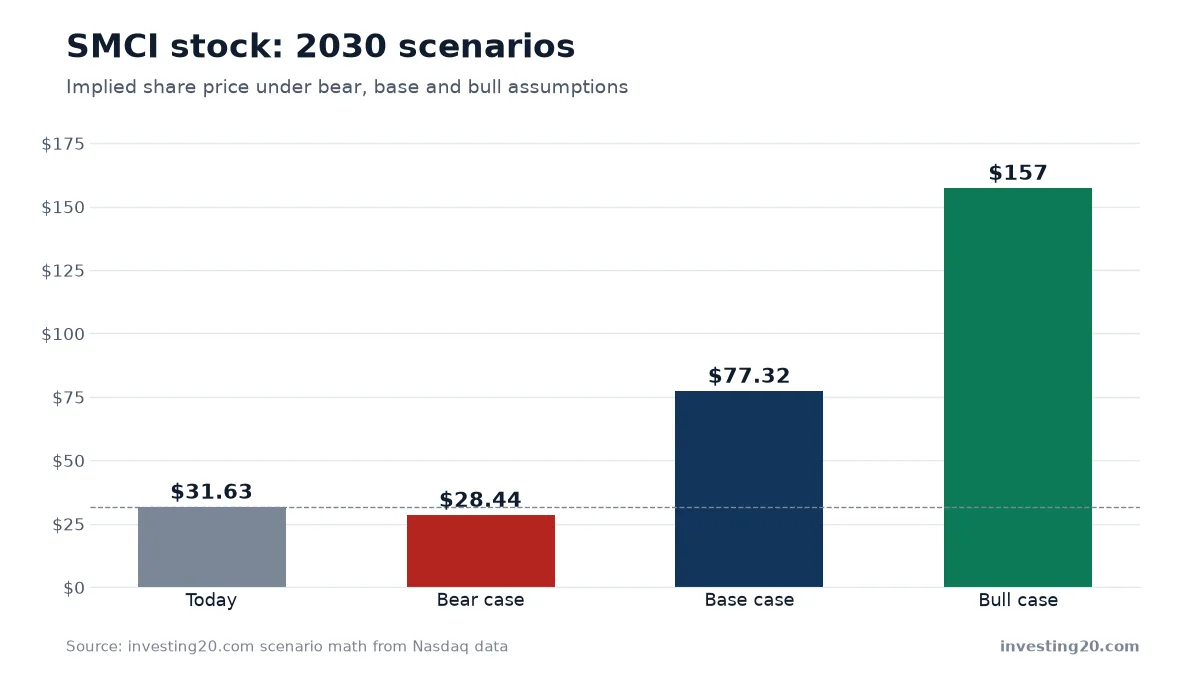
| Bear | 23% slowing to 5% | $65.9 billion | 0.3× | 739 million | about $28.44 (-10%) |
| Base | 47% slowing to 15% | $112.6 billion | 0.5× | 697 million | about $77.32 (+144%) |
| Bull | 70% slowing to 25% | $180.1 billion | 0.6× | 670 million | about $157.28 (+397%) |
The bear case
In this scenario, annual revenue growth slows quickly from 23% down to 5%, averaging roughly 14% per year through 2030. That brings total revenue to $65.9 billion. Ongoing margin pressure and intense hardware competition pull the valuation multiple down to 0.3 times sales. Across 739 million diluted shares, the implied stock price is about $28.44, representing a 10% decline from current levels.
The base case
In the base case, revenue growth moderates from 47% down to 15%, averaging about 30% per year and taking total sales to $112.6 billion in 2030. The market maintains today’s modest valuation multiple of 0.5 times sales. With 697 million shares outstanding, this results in an implied share price of roughly $77.32, a gain of 144% from today’s price.
The bull case
The bull scenario assumes enterprise data center expansion remains relentless. Revenue growth starts at 70% and tapers to 25%, averaging about 47% annually and pushing 2030 revenue to $180.1 billion. With strong market share and solid profitability, the price-to-sales ratio edges up slightly to 0.6. Spread across 670 million shares, the implied price reaches about $157.28, representing a 397% gain.
The core takeaway from these scenarios is that because SMCI trades at such a low multiple today, even a sharp slowdown in growth could keep the share price relatively stable, while sustaining moderate growth could yield substantial long-term gains. Investors tracking disruptive companies often face these broad valuation divergences; for another perspective on scaling hardware, see our Rocket Lab (RKLB) stock forecast.
Risks to weigh
Before making any investment decision on Super Micro, you need to balance the low valuation against several structural risks:
- Customer concentration: A significant share of high-end server demand comes from a small handful of cloud platforms and data center operators. Losing even one major customer allocation can immediately dent quarterly sales.
- Supply chain and component access: Super Micro relies on advanced processors, memory chips, and power components from third-party suppliers. Any component shortages or delivery bottlenecks can delay rack shipments.
- Margin compression from competition: Server assembly is an intensely competitive industry. Rival hardware makers can compete aggressively on price, which threatens Super Micro’s gross margins over the long run.
- Valuation overhang: Even with trailing net income of $2.2 billion, the market prices SMCI at less than 10 times earnings. That discounted multiple reflects investor skepticism about past governance questions and the durability of the AI spending wave.
What to watch next
If you hold SMCI or are waiting for a better entry point, keep an eye on upcoming quarterly earnings reports to see if top-line growth can remain above the 30% mark. Specifically, watch whether gross profit margins hold steady as next-generation server architectures roll out, and track whether consensus EPS estimates for fiscal 2027 and 2028 revise upward from their current marks of $3.94 and $4.90.
FAQ
What is the SMCI stock forecast for the next 12 months?
Wall Street analysts tracked by Nasdaq have an average 12-month SMCI price target of $39.67, representing about a 25.4% gain from the October 2026 price of $31.63. Targets range widely from a low of $15.00 to a high of $51.00, reflecting mixed sentiment across 14 covering analysts.
What is the consensus analyst rating on SMCI?
As of October 2026, the consensus rating leans cautious, with 9 hold ratings, 2 buy ratings, and 3 sell ratings. Despite strong recent earnings surprises, most analysts remain on the sidelines.
Can SMCI reach $100 by 2030?
In our 2030 base-case scenario, SMCI could trade around $77.32 if sales hit $112.6 billion, while the bull-case scenario projects an implied price of about $157.28 if revenue scales to $180.1 billion and its valuation multiple expands slightly to 0.6 times sales.
Market data and financials: Nasdaq. Scenario math: investing20.
This article is for information only and is not investment advice. Do your own research before investing.